Your home can be more than a place to live. As you pay down your mortgage and your property's value changes, you may build equity that can potentially be used for renovations, major expenses, debt consolidation, or other financial goals. Before borrowing
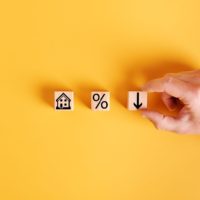
Buying a home comes with a new monthly payment, and some buyers may prefer a gradual transition into that expense. A 3-2-1 mortgage buydown can temporarily reduce the principal and interest portion of your mortgage payment during the first three years. Ho
Saving for a down payment can feel like one of the biggest challenges of buying a home. A clear savings target and a realistic plan can make the process much more manageable. Better yet, you may not need the 20% down payment many buyers assume is required
Your credit can play an important role when you apply for a mortgage. Lenders review your credit history along with your income, debts, assets, and other financial information to evaluate your application and determine which loan terms may be available. U
A home equity line of credit, commonly called a HELOC, allows homeowners to borrow against available home equity without replacing their existing first mortgage. Traditional HELOCs usually have variable interest rates, which means the rate and payment can
Coming up with the money needed to buy a home can be challenging, especially for first-time buyers. If you are using an FHA loan, eligible gift funds may help cover some of the cash needed for your purchase. FHA gift funds can potentially be used toward y